Ages 20 to 50
The best time to set up a funeral plan is before you think you need it
Starting between 20 and 50 means lower premiums, more interest growth, and earlier protection.
Why starting young pays off
Starting earlier can turn a smaller monthly payment into a paid-up plan.
Lower monthly premiums
The same coverage costs less each month at 35 than at 65 or 75.
More years of growth
More time allows potential growth to help offset rising funeral costs.
Easier health qualification
Qualifying is often easier before health changes limit your options.
Coverage that starts sooner
Illness and accidents affect young people too, and a funeral costs the same at 45 as at 85. Coverage can start right away.
Sheltered from life's surprises
A properly structured plan will pay the funeral home directly and stay outside the estate.
Sorted before retirement
Handle the cost while you're still earning, so it need not compete with a fixed retirement budget later.
Afford more of what matters
Starting earlier can make a fuller service affordable and protect your plans before retirement limits the budget.
Peace of mind for your family
Written, funded wishes spare loved ones from guessing, arguing, or borrowing.
More travel?
The worldwide travel plan will cover bringing you home after a death abroad. Set it up young and more of your trips will be covered.
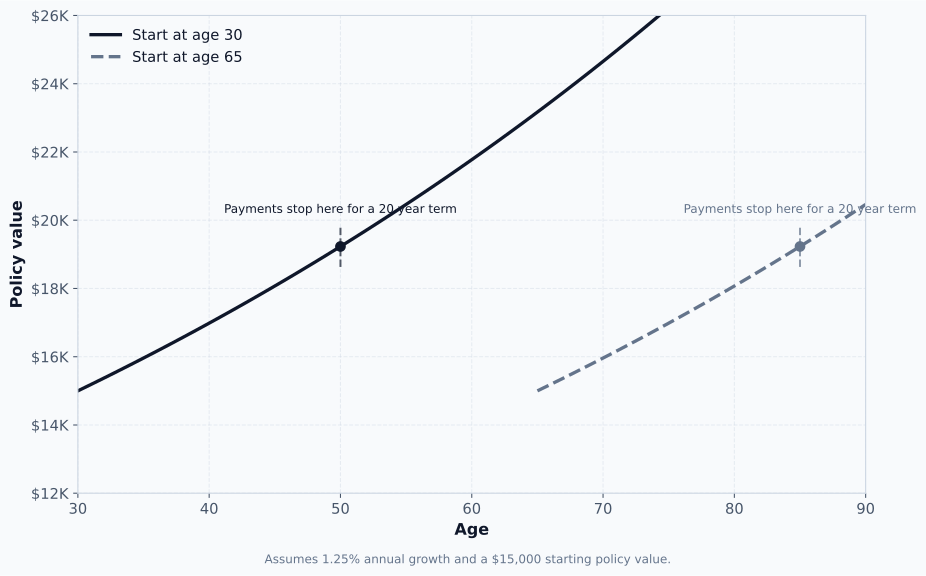
How a $15,000 policy grows at 1.25% per year
The same $15,000 policy is shown starting at 30 and 65, with illustrative 1.25% annual growth.
Start at 30
$23,170
value at age 65
Start at 65
$15,000
value at age 65
Extra growth at 65
$8,170
more coverage for the earlier starter
Starting earlier vs. waiting
Premiums depend on age, coverage, and term. Earlier usually costs less.
- Monthly premium: Lower; starting later means higher premiums.
- Years to pay: Longer term options; waiting limits your options.
- Health questions: Fewer complications; waiting means more likely to affect placement.
- Coverage start: As soon as paperwork is finalized; waiting leaves you unprotected.
- Growth: More years to compound; waiting means less growth before a claim is made.
What this really means
A 30-year-old funding $15,000 over 20 years generally pays less monthly than a 55-year-old funding it over 10.
That means earlier protection with less budget pressure.
Myths about starting young
I'm too young to think about a funeral funding plan.
That's exactly when it's cheapest. You don't buy it because you're planning to need it soon; you buy it so your family never has to worry about it.
I don't have dependents, so I don't need it.
Even if no one depends on your income, someone still has to pay for a funeral. Parents, siblings, or an executor will be left with the bill if nothing is set aside.
I can just save the money myself.
You can, and some people do. But a formal plan keeps the money sheltered, allows it to grow, and can pay it directly to the funeral home so it doesn't get spent on other costs first.
I'm young and healthy, so this doesn't apply to me.
Although we associate dying with old age, young people pass away from illness and tragic accidents all the time. And when they do, their families pay the same funeral home prices as the family of someone who dies at eighty.
I'll wait until I'm older.
Waiting means higher premiums and a higher chance that a change in your health limits your options. The best time to lock in a rate is before you need it.
What a young starter's plan can cover
A plan may also cover travel home, legacy gifts, and final administration.
- Funeral home services, cremation, or burial
- A monument, marker, or headstone
- Repatriation to another city, province, or your home nation
- Flowers, reception, and death certificates
- A leftover gift to your children, grandchildren, or a charity
- Final document aftercare and executor support
Bigger responsibilities may need more coverage
Final expense covers funeral costs. Standard life insurance can protect children, a mortgage, or a business.
Young kids at home
Term life can provide a lump sum that covers childcare, education, and daily living costs until your children are grown.
Mortgage or major debt
A policy matched to your mortgage balance can keep the family home off the market and remove that monthly pressure right away.
Business obligations
If partners, employees, or lenders rely on you, life insurance can fund succession plans, buy-sell agreements, and outstanding business loans.
Term, whole life, and children's policies
Compare standard life insurance costs, terms, and insurers alongside final expense coverage.
Get your numbers while they're lowest
Get free monthly figures for several coverage levels, with no obligation.