How it works
From first question to peace of mind, in four steps
Here is the full process for setting up a funeral funding plan in Ontario.
A free, no-pressure conversation
20–30 minutes
We talk by phone or meet in person in Eastern Ontario to discuss what you want covered, your age, and a few general questions.
Bring your spouse or adult children if you wish. There is no charge, pressure, or commitment.
Choose your options and how you'd like to pay
A few minutes, usually on the same call
I compare coverage amounts and payment terms to find a plan that fits your needs and budget.
Choose a 1, 3, 5, 10, 15, or 20-year term, or one payment. Longer terms lower the monthly cost but increase the total cost of the insurance component.
Optional travel, document aftercare, and extra coverage may also be available.
Complete a short application
About 30 minutes
Complete the one-page application in person or by phone, and name your beneficiary.
No medical exam is required. Some plans ask a few health questions.
Your plan is secured and your wishes are recorded
Coverage starts as soon as paperwork is finalized
Once finalized, coverage begins according to the contract. Pay monthly or once. The plan grows and is protected by Assuris, subject to applicable limits.
Record your wishes in the planning guide, then tell your family the plan exists. Your funeral director handles the details.
What the money can be used for
Funds pay your chosen funeral home for services and related expenses. Any remainder goes to your beneficiary, bypassing your estate and probate.
What your premiums are actually paying for
Each premium helps pay up the policy and covers the insurer's risk of paying the full benefit before your term is complete.
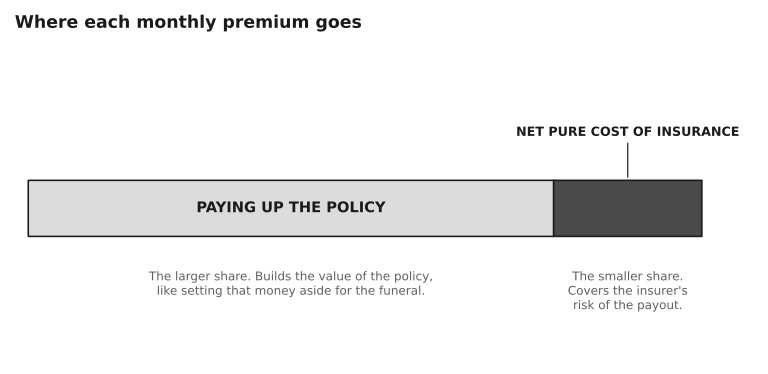
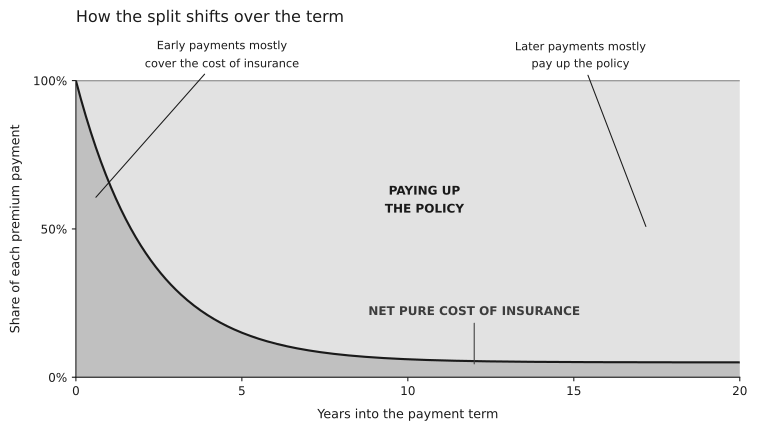
Like a mortgage, the split changes over time. More of each later payment goes toward paying up the policy until no further payments are due.
What happens when my term is complete?
Finishing payments does not end the coverage. Like a paid-off car loan, the policy becomes yours outright.
Once paid up, coverage continues according to the contract, without losing value simply because payments stop.
This is still confusing, can you explain it to me in the simplest way possible?
It kind of works like a special savings account for your funeral that is insured and can grow over time.
If your goal is to save $10,000 over 10 years, your policy value would be $10,000 and your term would be 10 years. Payments build value and includes the cost to insure the policy. If you die early, the insurance pays the full $10,000. After 10 years, your $10,000 (plus interest) is saved up and ready to be used for your funeral.
Exact growth, payout timing, and contract details depend on the specific policy, and I'll walk you through those before you sign anything.
Starting earlier makes it easier
Starting in your 30s or 40s usually means lower costs and easier health qualification than waiting. If you're between 20 and 60, read why starting young pays off.